Related Resource: Explore our complete breakdown on credit card travel insurance in the UAE.
Confirm in 5 seconds if your passport or visa type legally requires zero-deductible medical coverage before boarding using our free UAE and GCC visa insurance requirement checker.
Related Resource: Explore our complete breakdown on travel insurance deductible.
Related Resource: Explore our complete breakdown on best travel insurance UAE.
When you book flights and hotels on a non-refundable basis, you take on timing risks tied to work approvals, family priorities, or destination disruptions. That’s why many residents consider trip cancellation insurance UAE cover as a safety net. This page zeroes in on which reasons are actually covered, the common pitfalls and exclusions, and how non-refundable bookings interact with cancellation terms. For broader context (medical cover, baggage, trip delay, and more), see our pillar guide to travel insurance for UAE residents[A].
cancellation exclusions
non-refundable bookings
trip interruption
1) What Is Trip Cancellation Insurance?
Trip cancellation cover reimburses your prepaid, non-refundable travel costs when you must cancel your trip before departure due to a reason specified in the policy. Eligible expenses often include flights, accommodation, tours, cruise deposits, and prepaid excursions booked ahead of travel.
It is distinct from medical cover (which pays for treatment abroad) and from trip interruption (which applies once your journey has started). If you’re comparing the value of medical benefits versus cancellation protection for visa-bound routes, our analysis in Schengen: Medical vs Trip Cancellation Cover[B] can help frame the trade-offs without repeating visa rules here.
2) Covered Reasons for Cancellation
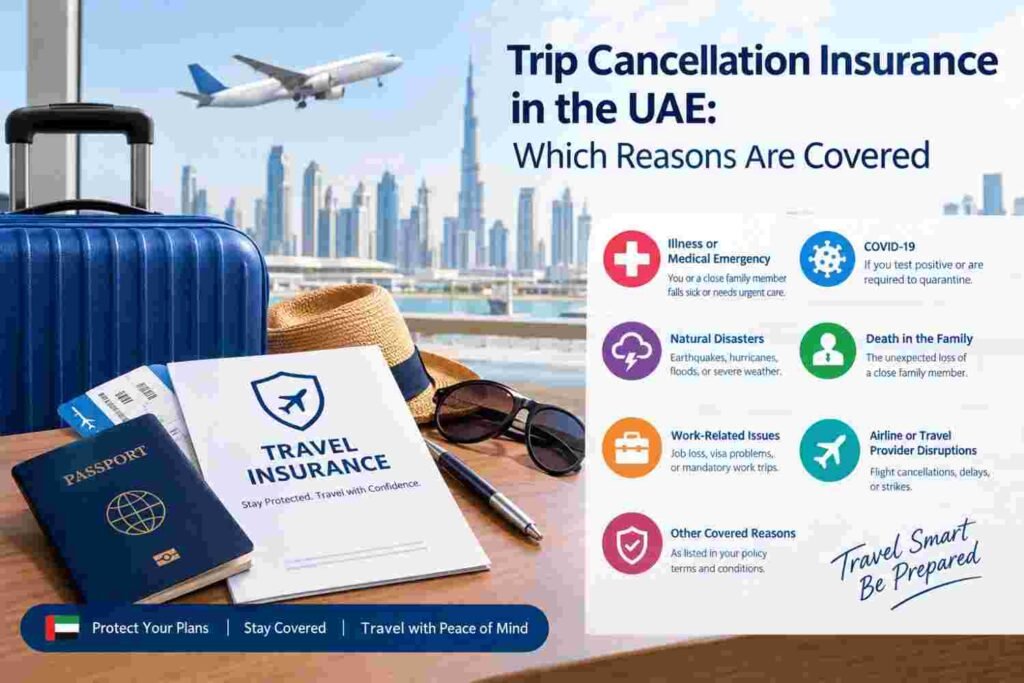
Policy wordings vary by insurer, but most UAE policies share a core set of “insured perils” for cancellation. Typical covered reasons include:
- Sudden serious illness or accidental injury of you or a covered travel companion resulting in medical unfitness to travel, certified by a licensed physician.
- Death of the policyholder, a travel companion, or a close family member.
- Hospitalisation or medically necessary procedures immediately before departure.
- Mandatory quarantine ordered by a doctor or public health authority.
- Natural disasters at the destination (e.g., earthquake, flood) or events rendering the accommodation uninhabitable.
- Terrorism or civil unrest advisories affecting the destination, typically when government warnings advise against travel.
- Involuntary job loss or redundancy (usually after a minimum employment period; resignation is excluded).
- Legal obligations that cannot be postponed (e.g., jury duty or court summons in your country of residence).
- Serious damage to your residence shortly before departure (fire, flood, burglary), making it unsafe to leave.
- Recall to duty for military, civil defense, or essential services personnel.
| Covered Reason | Examples of Acceptable Proof |
|---|---|
| Sudden illness/injury | Medical certificate stating you are unfit to travel; test results; hospital admission report |
| Death of close family member | Death certificate plus proof of relationship (e.g., Emirates ID family book or legal document) |
| Mandatory quarantine | Public health order or doctor’s note specifying isolation dates |
| Natural disaster at destination | Government advisory, civil defense report, or credible media confirming the event and dates |
| Job loss (involuntary) | Employer termination letter stating redundancy/layoff and effective date |
| Home uninhabitable | Police/civil defense report; insurer home-claim reference confirming severity |
Note: Terms like “close family” and “travel companion” are defined in each policy. See the grey areas below, and consult your insurer’s definitions in the schedule of benefits or glossary.[2]
3) Edge Cases and Grey Areas (UAE Context)
Even when the event seems straightforward, eligibility can hinge on definitions, timing, and documentation:
For broader context on how cancellation stacks up against other benefits (without duplicating visa specifics), refer to our analysis in the medical vs cancellation comparison[B].
4) Common Cancellation Exclusions
Exclusions are where most disputes happen. UAE policies commonly exclude:
| Excluded Reason | Typical Rationale |
|---|---|
| Change of mind or lack of desire to travel | Not an insurable event; considered voluntary |
| Undeclared or excluded pre-existing conditions | Known risks at purchase time are generally not “unforeseen” |
| Visa refusal or delay | Treated as an administrative/foreseeable risk in most policies |
| Work schedule changes or voluntary resignation | Business/voluntary decision, not a covered peril |
| Financial default of airline/hotel (basic plans) | Requires a “supplier failure/default” add-on where available |
| Illegal acts, intoxication, or reckless behavior | General policy exclusion across travel benefits |
If your travel purpose involves consular or visa processes, coverage nuances can differ by route. For a comparison of benefit priorities (without reproducing visa rules), see Schengen: Medical vs Trip Cancellation Cover[B].
5) How Cover Applies to Non-Refundable Bookings
Non-refundable bookings are the core use case for cancellation cover. The insurer steps in to reimburse documented, prepaid, non-refundable amounts when a covered reason forces you to cancel:
- Sum insured cap: Payouts are limited by your chosen cancellation sum insured; choose a limit that matches all prepaid components.
- Purchase timing: You must buy the policy before the event becomes reasonably foreseeable (e.g., before symptoms start or redundancy is announced).
- Waiting periods: Some plans impose a 24–72 hour waiting period after purchase for cancellation benefits to activate.
- Partial cancellation: If one traveler in a group cancels for a covered reason, their share is typically reimbursable.
- Refund offsets: Any supplier refunds, credits, or vouchers are deducted from the claimable amount.
- Fees and taxes: Government taxes and carrier-imposed fees may be refundable directly from the airline; insurers usually cover only what remains non-refundable.
6) Trip Interruption vs Trip Cancellation
Both protect trip value, but their timing and outputs differ:
| Feature | Trip Cancellation | Trip Interruption |
|---|---|---|
| When it applies | Before your scheduled departure | After your trip has started |
| What’s covered | Prepaid, non-refundable trip costs | Unused prepaid portion + additional return travel costs |
| Typical triggers | Illness, death, disaster, involuntary job loss | Medical emergency abroad, serious incident at home |
Not sure which applies to your case? The documentation and submission timelines are explained in our UAE resource on How to File a Travel Insurance Claim in UAE[C] (we don’t repeat the filing steps here).
7) What Proof Do Insurers Ask For?
While each provider has its own checklist, claims teams in the UAE tend to ask for:
- Policy certificate and schedule showing cancellation coverage limits.
- Original booking confirmations and proof of payment (invoices, bank statements).
- Supplier cancellation invoice itemizing the non-refundable amounts.
- Reason evidence:
- Medical: physician statement declaring unfit to travel; test results where relevant.
- Bereavement: death certificate plus proof of relationship.
- Job loss: termination letter showing involuntary redundancy and date.
- Home damage: police or civil defense report; insurer home-claim reference.
- Advisories/disasters: official government advisory or civil authority notice.
- Completed claim form with signatures and dates.
For submission channels, cut-off times, or follow-ups, use the UAE claims guide: How to File a Travel Insurance Claim in UAE[C].
8) Choosing Cancellation Cover That Fits
Match your cover to your booking style and risk profile:
Related Resource: Explore our complete breakdown on essential travel insurance coverages.
- Sum insured sizing: Add up flights, accommodation, tours, and prepaid extras. Insure the maximum non-refundable amount you could lose.
- Supplier default: If you’re booking niche airlines or prepaying small operators, consider plans with a supplier failure/default add-on.
- CFAR (Cancel For Any Reason) add-on: Some premium policies offer CFAR (typically reimbursing 50–75% if purchased within a short window after initial booking). Availability varies; read terms carefully.
- Pre-existing conditions: If you manage ongoing conditions, look for policies offering declared-condition extensions or stability periods.
- Multi-trip vs single-trip: Frequent travelers may find annual multi-trip plans with cancellation limits cost-effective.
- Documentation discipline: Keep fare rules, rate codes, and cancellation terms. Insurers can only reimburse what is provable and non-refundable.
For an end-to-end understanding of how cancellation sits alongside medical, baggage, and delays, circle back to the foundation guide: travel insurance for UAE residents[A].
9) Real-World Scenarios: Covered vs Not Covered
Scenario A — Covered: Sudden illness before departure
Two days before flying, you develop acute appendicitis and undergo emergency surgery. A licensed physician certifies you are unfit to travel for three weeks. You submit your hospital admission, medical certificate, and supplier cancellation invoices. Result: Claim approved up to the cancellation sum insured, minus any supplier refunds.
Scenario B — Likely Excluded: Visa refusal
You booked non-refundable flights ahead of a destination’s visa decision. Your application is refused. Most UAE policies exclude visa refusal as a foreseeable risk. If your route has consular nuances, compare benefit priorities here: Schengen: Medical vs Trip Cancellation Cover[B].
Scenario C — Covered: Home becomes uninhabitable
Two days before departure, a burst pipe floods your apartment. Civil defense confirms severe damage. You cancel to manage the emergency. With official reports and invoices, the insurer reimburses non-refundable costs under the home-damage trigger.
Scenario D — Not Covered: Employer changes your leave dates
Your supervisor withdraws leave approval due to a project deadline. Schedule changes by your employer are generally excluded. If you anticipate volatility, consider refundable fares or CFAR extensions (where available) and ensure your overall travel insurance plan[A] reflects that risk appetite.
Scenario E — Interruption (Not Cancellation): Family emergency mid-trip
Midway through your holiday, a close relative is hospitalised back home. You cut the trip short and fly back. This is a trip interruption claim (unused portion + return costs), not cancellation. For documentation specifics, see the UAE claim guide: How to File a Travel Insurance Claim in UAE[C].
Frequently Asked Questions
Does trip cancellation insurance in the UAE cover change of mind?
No. Standard policies exclude voluntary cancellations. Some offer a CFAR (Cancel For Any Reason) add-on, usually reimbursing 50–75% if purchased shortly after initial trip payment; conditions vary by provider.
Is a visa refusal a covered reason for cancellation?
Generally not. Most UAE policies treat visa refusal as a foreseeable administrative risk. For route-specific trade-offs, compare medical vs cancellation priorities here: Schengen: Medical vs Trip Cancellation Cover[B].
Are airline schedule changes covered?
Not usually under cancellation. If the carrier changes or cancels flights, your first recourse is the airline (refunds/re-routing). Insurance may respond to knock-on costs under delay or missed connection sections, but that’s separate from cancellation.
Can I claim for partially used hotel nights if I cut the trip short?
That’s typically a trip interruption claim. You’d seek reimbursement for unused prepaid nights plus necessary return transport, subject to policy limits.
Is pregnancy covered?
Normal pregnancy is not a cancellation trigger. Some policies may cover unforeseen complications within defined gestational limits; known high-risk diagnoses are usually excluded unless specifically endorsed.
What documents do I submit to the insurer?
Expect policy details, booking proofs, supplier cancellation invoices, and evidence supporting the reason (medical notes, death certificate, termination letter, etc.). For submission channels and timelines, use How to File a Travel Insurance Claim in UAE[C].
Do all insurers treat “close family” the same way?
No. The definition varies by policy. Always check the glossary/definitions section of your specific insurer’s wording.[2]
✅ Actionable next step
- Compare cancellation vs other benefits without duplicating visa rules: Medical vs Trip Cancellation comparison[B].
- Understand how cancellation integrates with your full plan: travel insurance for UAE residents[A].
- When ready to claim, don’t guess the process—go here: How to File a Travel Insurance Claim in UAE[C].